Japan’s Wage-Inflation Pivot: A Structural Shift or a Policy Contradiction in the Making?

A Turning Point, or a Tension Point?
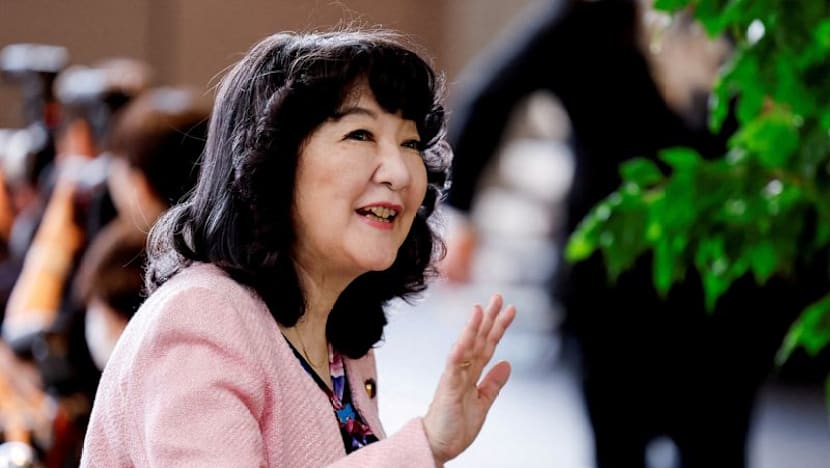
Japan’s economy stands at what its Finance Minister Satsuki Katayama describes as an inflection point — a transition from inflation driven by external cost pressures toward a more structurally embedded, wage-led inflationary cycle. The thesis she advances is broadly welcomed by economists who have long argued that Japan’s deflationary decades could only be broken by genuine wage growth. But the policy environment surrounding this claimed transition raises a sharper question: can a government simultaneously pursue expansionary fiscal measures and credibly support a central bank trying to cool prices?
That tension sits at the heart of Japan’s current economic moment, and it deserves more scrutiny than the Finance Minister’s reassurances invite.
The Bank of Japan’s Tightening Bet
The Bank of Japan raised its benchmark interest rate to 1.25 per cent in September — a 31-year high — responding to a confluence of pressures that include the energy shock stemming from the Iran war, robust global demand for AI-related goods and services, and the inflationary drag of a persistently weak yen inflating import costs. The BOJ’s concern is not merely that inflation is present, but that underlying inflation could overshoot its 2 per cent target in a way that becomes self-reinforcing. Rate hikes are the instrument of restraint.
Katayama, speaking before parliament on October 21, maintained that the government and the BOJ share no fundamental divergence of view. That is a carefully worded claim. Institutional harmony between a finance ministry and a central bank is always partly performative — both parties understand that public discord destabilises markets. What matters more is whether the policy actions of each institution actually pull in the same direction.
The Consumption Tax Cut and Its Contradictions
Prime Minister Sanae Takaichi’s administration plans to reduce the 8 per cent consumption tax on food items by two years starting from April next year — a measure explicitly designed to ease cost-of-living pressures on households. Alongside this sits a broader programme of government spending. Analysts have been direct in their concern: demand-stimulating fiscal policy, deployed precisely when the central bank is attempting to suppress demand-driven price growth through rate hikes, is not a neutral act.
Katayama acknowledged as much. She conceded that tax cuts generally function to push up inflation by stimulating demand — a candid admission that carries more weight than the reassurance that followed it. Her counter-argument rests on the idea that the government’s fiscal policy will be “responsible and proactive” in expanding Japan’s supply capacity rather than simply stoking consumption. The supply-side framing is analytically coherent in principle. In practice, the credibility of that argument depends entirely on the composition and sequencing of the spending — details that remain underspecified.
Supply-Side Framing as Political Cover
The supply-capacity argument is not without precedent. Targeted public investment in productive infrastructure, labour market reform or industrial capacity can, over a sufficient horizon, expand the economy’s non-inflationary potential. But the timeline matters enormously. Supply-side gains accrue slowly; demand-side stimulus hits quickly. If the consumption tax cut and associated spending boost household purchasing power in the near term — which is their stated purpose — the inflationary impulse will be felt well before any supply-side offset materialises.
This is the structural ambiguity that Katayama’s parliamentary statement does not resolve. And it is precisely the kind of ambiguity that markets, rating agencies, and the BOJ’s own policy committee will be watching closely.
Wage Growth as the Legitimate Prize
Beneath the policy friction lies a genuinely important macroeconomic development. Japan’s shift toward wage-driven inflation — if it is real and sustained — would represent a meaningful break from three decades of stagnation in which productivity gains consistently failed to translate into household income growth. The country’s corporate sector accumulated cash reserves and suppressed wage bills even as output per worker improved. Workers, in short, did not share in the gains.
A durable wage-price dynamic, anchored in collective bargaining outcomes and structural labour tightness, would validate the BOJ’s long-held thesis that Japan could normalise monetary policy without triggering a deflationary relapse. It would also give the government’s fiscal expansion a more defensible macroeconomic rationale — spending into a wage-growth environment is categorically different from spending into a cost-push, import-driven inflationary episode.
The critical question is which phase Japan is actually in — and whether the transition Katayama describes is already underway, or merely anticipated. That distinction is not semantic. It determines whether the government’s fiscal posture is timely support for a structural shift, or premature stimulus that risks overheating an economy still finding its footing.
The Implication
Japan’s policy establishment is betting, with some justification, that the country has entered a new macroeconomic era. But the bet carries real execution risk. The BOJ’s rate hikes and the government’s consumption tax cut are instruments pointing in opposite directions, even if both are framed as serving the same long-run objective. Katayama’s insistence that no gap exists between government and central bank thinking is reassuring in tone but incomplete in substance. The coherence of Japan’s economic strategy will ultimately be judged not by the harmony of ministerial statements, but by whether wage growth proves durable enough to justify the fiscal risks being taken in its name.